


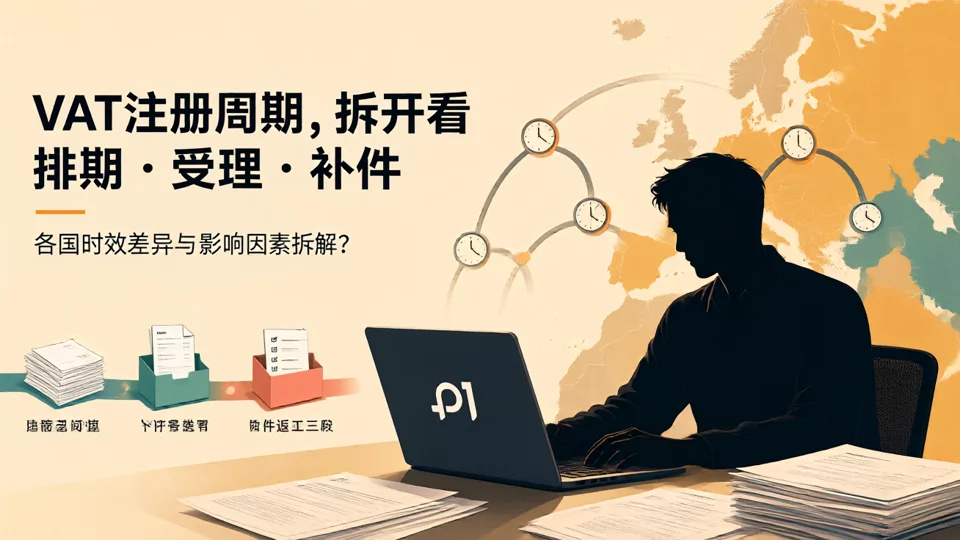
First, here is a usable reference range: with complete documents, UK VAT commonly takes 2–4 weeks to be issued; Germany, Italy, and Spain mostly take 4–8 weeks; France usually takes 3–6 weeks; Middle East markets such as the UAE and Saudi Arabia commonly take 2–6 weeks depending on the registration entity and whether a local agent is required. These are common ranges based on actual scheduling by service providers and sellers, not official timelines promised by tax authorities. Any claim of "guaranteed issuance in two weeks" should not be written into your schedule.
Two misconceptions are most common. The first is treating the "issuance time" promised by an agent as the tax authority's processing time, ignoring the queue and pre-review before submission. The second is comparing cases with different registration entities and different warehousing and fulfillment models against each other—for example, using the timeline for a Hong Kong company registering in Germany to gauge the progress of a Chinese company registering in Italy. The preconditions differ, so the conclusions drawn from such comparisons are meaningless.
A more practical approach is to break the total duration into three stages: tax agent scheduling before submission, tax authority acceptance and processing, and rework from document supplements. Only by identifying which stage you are stuck in can you know whom to follow up with and what to supplement.
I. The Registration Timeline Consists of Three Stages, Not a Fixed Number of Days
- Tax Agent Scheduling: From signing the contract to the documents actually being submitted into the tax authority's system, including document pre-review, translation, notarization, and queueing for a number. During peak filing season, this stage can account for half of the total duration.
- Tax Authority Acceptance and Processing: The tax authority accepts the application, assigns a tax number, and issues a notice. At this stage, sellers can hardly speed up the process; they can only ensure the receipt details are complete and contact information is reachable.
- Supplementary document rework: Tax authority inquiries and requests for additional proof of address or business explanation. Each back-and-forth often takes weeks, and this is the real source of most “overdue” cases.
Therefore, asking the service provider “On what date were my documents submitted, and what is the tax authority receipt number?” is far more useful than asking “How much longer will it take?” The former is a verifiable fact; the latter is often just an estimate.
II. Comparison of Common Registration Timeline Ranges in Major Countries
Differences in the range mainly come from three things: the level of digitization of tax authority systems, whether a local contact or local tax representative is mandatory, and whether the registration entity is a local entity. The UK process has a higher level of digitization, and the document checklist is relatively fixed; Germany, Italy, and Spain require more detailed proof of address and explanations of business substance; Middle East markets commonly require the involvement of a local agent, and the agent's own response speed is directly included in the total duration.
III. Why do some applicants for German VAT take two weeks while others take two months?
Differences within the same country are often greater than differences between countries. The following variables determine which end of the range you fall into.
| Variables | Why the timeline gets extended | Actionable responses |
|---|---|---|
| Type of registration entity | Chinese companies, Hong Kong companies, and local entities require different supporting documents, and the tax authority's verification depth also differs | First confirm whether the tax agent has recent cases involving the same type of entity, then decide which entity to use for the application |
| Proof of address and local contact | Some countries require a verifiable business address or local contact; if the materials do not comply, the application will go directly into the supplementary-documents process | Prepare address evidence consistent with the entity in advance; do not borrow someone else's address at the last minute |
| Translation and notarization quality | Missing pages in translated documents, unclear stamps, and inconsistent information will all lead to rejection and resubmission | Before submission, have the tax agent conduct a page-by-page check and allow time for redoing documents |
| Tax authority inquiries and supplementary documents | When the tax authority has doubts about the authenticity of the business, it will issue an inquiry letter, and the response period is measured in weeks. | Assign a designated person to monitor the mailbox and tax agent notifications, and begin preparations on the day the inquiry is received. |
| Tax agent scheduling and peak season | At the beginning of the year and before filing deadlines, tax agents have a concentrated caseload, and submission milestones get pushed back. | Lock in the submission milestone in advance and require a planned submission date rather than 'as soon as possible'. |
Use this table as a self-check checklist: if even one of the five variables is not ready, your timeline will drop back a level. The completeness of registration materials is tied to subsequent filing obligations; for reference, you can refer toCross-Border E-Commerce Compliance Policy Implementation Checklistand review the filing and tax evidence chain section in it together.
Four: From submitting materials to number issuance: the step most likely to stall in the timeline
- Prepare basic materials such as entity documents, proof of address, and business description, and confirm that the names and addresses on all documents are exactly consistent.
- Engage a licensed tax agent and specify the person responsible for pre-reviewing the materials and the planned submission date.
- The tax authority accepts the application and issues a receipt; record the receipt number and acceptance date.
- Respond to tax authority inquiries or requests for supplementary documents item by item, and keep records of each submission.
- After the number is issued, check whether the tax number information matches the registered entity, and apply for correction immediately if any errors or omissions are found.
- The tax number is truly usable only after it is updated in the platform backend and the filing cycle and first filing date are confirmed.
The most easily underestimated steps in the timeline are Step 4 and Step 6. Requests for supplementary documents aside, platform verification is also often treated as 'just a click and done'; in reality, the platform's verification of the tax number and entity information, as well as secondary review at some sites, may take another few days to a week or two. Platform-side tax information requirements are subject to Seller Central notifications and official help pages; you can cross-check againstAmazon Seller Central Help Centerthe tax and compliance-related entries in it to verify the current requirements.
V. Determine whether your registration schedule is normal: three checkpoints
- Is there an official acceptance receipt?:If there is only a signed contract but no receipt, it means the documents are still with the tax agent; at this point, chasing the tax authority is meaningless.
- Are there any unanswered inquiries?: Inquiry letters are often sent to the tax agent or registered email; if no one handles them for more than a week, the timeline will be passively extended.
- Is the tax agent merely queuing without submitting? : Request the planned submission date and current queue position. If they fail to provide specific milestones twice in a row, consider changing the service provider.
When all three checkpoints are passed and the timeline still clearly exceeds the upper limit of the range, then consider submitting additional business explanations or changing the tax agent—rather than frequently switching providers from the start, since changing the service provider itself will also reset the schedule.
Frequently Asked Questions
Can I pay to expedite VAT registration?
What can usually be accelerated is only the preparation stage before submission, such as priority review and expedited translation and notarization. The processing order on the tax authority side is generally not controlled by the service provider, and any claim that the tax authority's queue can be bypassed needs to be verified.
How should sales generated during registration be handled?
It depends on where the sale occurs and whether the platform withholds and remits taxes; supplementary filings may be required after registration. Keep a record of the date and amount of each sale, and after the tax number is issued, let the tax agent determine how to handle it—do not wait until the filing period to look back.
Does the tax number being issued mean I can list products immediately?
Not necessarily. You also need to complete the platform backend information update and possibly a second verification; some marketplaces require the tax number's effective date to be earlier than the sales date. Include the platform review time in your scheduling.
Will changing the warehouse address during registration lengthen the timeline?
In most cases, this is an update to registration information rather than a re-registration, but the change may trigger tax authority verification or requests for additional documents, so allow time in the schedule; involving warehousing in different countries may trigger new registration obligations.

