


A category may be hot on platform rankings and have an attractive purchase price, but once certification fees, first-leg freight, returns, and advertising costs are added, net profit may leave only a very thin margin. Such failures are usually not due to poor judgment but to failing to set elimination conditions before investing. The core of the cross-border e-commerce product selection methodology is to turn demand validation, compliance screening, profit calculation, and small-order validation into four gates: each gate has passing evidence and stop conditions; if evidence is insufficient, exit rather than doubling down on intuition.
Set stop conditions first: the four gates of the product selection process
- Demand validation: prove that people are willing to pay to solve a specific problem, and do not mistake short-term popularity for long-term demand.
- Compliance screening: a verifiable basis can be found for all four categories: platform access, product certification, tax and fee declaration, and advertising data.
- Profit calculation: calculate the break-even selling price and affordable customer acquisition cost, and leave margin for returns and compliance.
- Small-order validation: use the first batch of orders to validate quality, fulfillment, and actual conversion, then decide whether to scale.
The order cannot be reversed: if compliance or profit does not pass, stop even if demand is hot.
Demand validation: use three types of evidence instead of gut feeling
Put platform search terms, category rankings, and off-platform search trends in the same table to see whether they point in the same direction; looking at just one ranking list can easily mistake short-term traffic for demand. The second type of evidence comes from competitor reviews: whether negative reviews cluster around the same solvable problem, and whether return reasons point to packaging, size, instructions, or quality. The third type is low-cost testing: landing pages, inquiries, or small-budget ads; observe whether clicks lead to add-to-cart or qualified inquiries, rather than merely buying cheap clicks.
Set thresholds against your own baseline, not fixed industry numbers. If ad click-through rate is below the historical average, add-to-cart shows no improvement, and most inquiries are price comparisons, do not proceed to the next stage. When the three types of evidence conflict, gather more evidence first; do not replace stop conditions with 'let's try again.'
Compliance pre-screening: check four categories against 2024 policies first; if not passed, eliminate immediately
Cross-border e-commerce compliance policies in 2024 involve multiple levels—platform, product, tax, and advertising—and are updated by destination country and platform. Operationally, it is not about memorizing policy names but about building a 'verifiable evidence' file for each candidate category: if certifications cannot be completed, declaration standards cannot be clearly explained, or the basis for materials is unclear, pause immediately.
| Check category | What to check | Passing evidence | Stop condition |
|---|---|---|---|
| Platform access and prohibited sales | Category review, brand authorization, prohibited sales list, and store qualifications | Backend requirements are clear and documents are complete | Authorization required but unavailable |
| Product certification and labeling | Destination country certification, test reports, labels, and instructions | Reports cover the model and are within the validity period | Certification scope mismatch |
| Customs duties and tax declaration | HS code, country of origin, declared value, VAT/IOSS/EPR, etc. | Freight forwarder and tax treatment are consistent; taxes and fees can be included | Declaration basis is unclear |
| Advertising and data compliance | Privacy policy, cookie consent, efficacy claims, and influencer disclosure | Materials and landing pages are reviewable | Unclear data sources or efficacy basis |
Policies are time-sensitive: requirements applicable in 2024 may change in later years. Before committing, return to the platform rules page and official channels of the destination country to verify, and record the verification date and document version.
Turn the gates into a flowchart: continue, supplement evidence, or stop
The four gates are not parallel scoring but sequential elimination. If demand evidence is insufficient, stop at the first gate; if compliance basis is missing, do not proceed to profit calculation; if profit does not pass, do not do a small order; if the small order does not meet the standard, do not scale. The flowchart is for the team to align on “who provides what evidence” and cannot replace the original platform policy text.
Profit calculation: from gross margin to affordable customer acquisition cost
- Landed cost: purchase price, first-leg freight, tariffs/import duties, insurance and damage, calculated using a conservative exchange rate and declaration basis.
- Platform and fulfillment: commission, payment fees, warehousing, last-mile delivery, remote-area surcharges; for an independent site, also factor in payment disputes and plugin costs.
- Returns and after-sales: set a returns reserve and include return shipping, inspection, relabeling, and markdown for resale.
- Marketing expenses: advertising, influencers, content production; work backward from affordable CAC instead of spending first and looking for profit later.
- Compliance and tool cost allocation: certification testing, registration, label redesign, and subscriptions for operational tools such as ERP/customer service, amortized over first-batch sales.
Affordable CAC is approximately equal to selling price − landed cost − platform/payment/fulfillment − return reserve − compliance and tool allocation − target net profit. If the calculated CAC is lower than what existing channels can achieve, you should stop or change the packaging or bundle. Tool subscription and team permission costs are easily missed and should be put back into the cost table.
Use a cost sensitivity chart to determine whether it is viable.
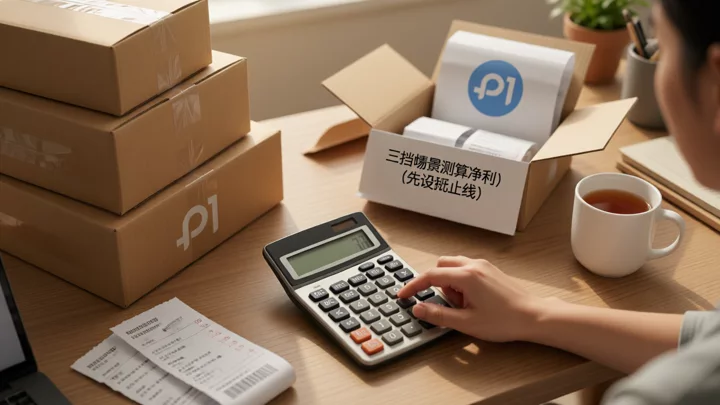
A single-point profit statement is not enough; at least create three scenarios—conservative, baseline, and optimistic: whether net profit remains positive when the selling price is lowered, the return rate rises, and advertising costs increase at the same time. Write the stop-loss line before testing; for example, if CAC is above the affordable value for two consecutive weeks and returns are concentrated in quality issues, stop adding investment. Also identify the most sensitive variable first: if a 5% drop in selling price breaches the break-even line, it indicates insufficient safety margin, and the product is not suitable as a main push item.
Small-order validation and stop-loss: what to inspect and accept before the first order
A small order is not 'try selling first'; rather, it tests the supply chain and demand with an acceptance checklist. Before the first order, inspect and accept the samples and documents: model and certification match, packaging labels compliant, quality inspection standards executable, and replenishment cycle clear. After launch, watch four types of signals:
- Quality and return reasons: whether returns are concentrated in the same defect, and whether they can be resolved through packaging or instructions.
- Fulfillment timeliness: whether the promised timeliness matches actual receipt, and whether there is a handling path for abnormal shipments.
- Real conversion: whether there are add-to-cart actions, inquiries, and repurchase intentions after clicks, rather than impressions only.
- Cash flow: whether funds tied up in advertising, inventory, and returns exceed the preset upper limit.
The condition for increasing investment should be multiple pieces of evidence meeting the standard at the same time, not a single explosive sales day. If any one of the following occurs—certifications cannot be completed, landed cost increases, returns are concentrated and cannot be fixed, or CAC remains above the upper limit—stop.
Frequently Asked Questions
Without historical sales data, how can we determine whether demand is not false demand?
Cross-validate across search term direction, the extent to which competitors' negative reviews can be resolved, and small-budget testing. If there are only impressions without add-to-cart or valid inquiries, treat it as failed; gather more evidence first before discussing stocking.
Can cross-border e-commerce compliance policies for 2024 and subsequent years still be directly applied?
This cannot be assumed. Platform access, certification, tax, and advertising rules will be updated. Before investing, recheck the official rules pages and retain the verification date and document version.
Which costs are most easily overlooked in profit calculations?
Return processing and resale discounts, amortization of certification and label revisions, subscriptions for operations tools and team permissions, and customer service time-zone costs. Put them into three scenarios instead of only calculating procurement plus shipping.
Should a small team validate first on a platform or on an independent website?
See which side can obtain real add-to-cart actions or valid inquiries faster, while the compliance basis is verifiable. Platforms have ready-made traffic but strong access and commission constraints; independent websites are more flexible, but customer acquisition costs must be validated first.

