


For an order with a sale price of 89 yuan and a product cost of 58 yuan, with platform commission at 11 yuan, the backend gross profit is shown as 20 yuan. However, after deducting the shipping cost of 40 yuan for 0.5kg billable weight, a customs duty surcharge allocation of 4 yuan, payment fees of 2 yuan, advertising allocation of 6 yuan, and a return reserve of 3 yuan, the net income for this order is −35 yuan. The 55 yuan difference is not due to an error in any single item; rather, the backend gross profit never included these costs in the first place.
Therefore, profit per order cannot be determined by simply looking at backend numbers; it must be recalculated based on net cash received.
Net profit per order = Actual amount received − Product cost − Billable weight shipping − Customs and clearance − Platform commission and payment fees − Advertising allocation − Return and loss reserves
First, fix three calculation standards: exchange rates are based on the platform settlement date, not the quotation date; an order is finalized only after the refund window closes and the refund is received; use ranges and rolling averages for customs duties and return reserves, rather than single-point values to feign precision.
How to allocate shipping costs to a single parcel: Calculating billable weight, volumetric weight, and surcharges separately
The logistics provider's quote of “how much per kilogram” is just a unit price. To apply it to a single parcel, you must pass through three stages: billable weight, basic handling fees, and surcharges.
Billable weight is the greater of actual weight and volumetric weight, then rounded up according to the channel's prescribed tiers. Volumetric weight = Length × Width × Height ÷ Channel Divisor. The divisor being 6000, 5000, or 8000 depends on the channel and cannot be applied across different channels.
Single shipment cost = Chargeable Weight × Unit Price + Registered/Handling Fee + Fuel Surcharge + Remote/Peak Season Surcharge + Return Fee (if applicable). For the example above with an actual weight of 0.38kg, the carrier rounds up to 0.5kg. At a quoted rate of 62 yuan/kg, the calculation yields 31 yuan. Adding the 6 yuan registered fee and the 3 yuan fuel surcharge, the actual cost is 40 yuan. The 9 yuan difference between the quote and the bill is entirely attributable to rounding and surcharges.
To determine if a channel is expensive, do not look only at the unit price. Use the actual bills from the last 10 shipments in the past month to reverse-calculate the effective unit price: Effective Unit Price = Total Freight ÷ Total Actual Weight. The effective unit price for the same 0.38kg SKU can vary by up to a factor of two across different channels, due to differences in rounding increments and registered fees. Billing discrepancies between channels can be compared againstCost differences between cross-border e-commerce small packages and dedicated line logistics.
How to Estimate Tariffs and VAT: Different Bases, Start with Ranges Then Build Dashboards
The calculation bases for tariffs, import VAT, and customs clearance fees differ significantly; mixing them up leads to persistent reconciliation issues. Tariffs are typically calculated on a CIF basis (Value of Goods + Freight + Insurance) or the declared value prescribed by the destination country, while the base for import VAT often includes tariffs and partial clearance costs. Specific tax rates are not provided here, as they depend on HS codes and destination country tax regulations; hardcoding a single figure will only skew pricing.
| Fee Item | Calculation Base | Data Source | Update Frequency | Common Errors |
|---|---|---|---|---|
| Import Tariff | CIF price or destination country declared value | HS code + destination country tariff schedule | When changing the commodity name or declared price | Discrepancy between declared and transaction price |
| Import VAT / GST | CIF + duties + (in some countries) customs clearance fees | Destination country tax authority | During tax rate adjustments | Back-taxes assessed after under-declaration |
| Customs clearance service fee | Per ticket, or per ticket + commodity name and quantity | Freight forwarder quotation | Each quarter | Small orders don't dilute costs |
| Back payments and penalties | Estimate based on invoices | Your own actual back payment records over the past 6 months | Monthly | Treat the range as a definite value |
Calculate your back payment reserve using your own data: divide your actual back payment amount over the past 6 months by the declared cargo value for the same period, then multiply the resulting ratio by the declared cargo value of new orders. This ratio varies by category and destination country, so you must track it separately by country. Before your VAT registration number is issued, the customs clearance method itself also impacts costs. For registration timelines, refer toBreakdown of VAT registration cycles and influencing factors by country.
How to allocate platform fees, payment fees, advertising, and returns per unit
The difficulty with these four items lies not in the amount, but in the granularity of allocation. Choosing the wrong granularity skews your net profit calculation per order, no matter how you do the math.
- Platform commission and payment fees: order-level.Calculated on the actual amount received per order. Note that the commission base differs by platform—whether it's the product amount or includes shipping—so don't just apply an average rate.
- Advertising: SKU-level.Ad spend for this SKU in the last 30 days ÷ number of orders for that SKU. For new products without historical data, use your target CPA as a substitute and mark it as 'estimated' on the dashboard.
- Return reserve: SKU × Country.Rolling 90-day return rate × average order value × (round-trip shipping + unsellable loss). Using the store-wide average return rate masks losses from high-return SKUs.
- Monthly subscription fees, ERP, and tool subscriptions: store-level.Don't include these in per-order calculations. Track monthly P&L separately, otherwise small orders will be loaded with unreasonable fixed costs.
For the specific structure of commissions and payment fees, refer to Major cross-border e-commerce platform commission rates and hidden cost accounting. Focus on the commission base, not the nominal percentage.
See the six-step deductions from selling price to net profit at a glance.
Walk through a sample order completely: selling price 89 yuan, minus product cost 58 yuan, charged weight shipping fee 40 yuan, customs and clearance 4 yuan, platform commission 11 yuan, payment fee 2 yuan, ad cost allocation 6 yuan, return reserve 3 yuan, resulting in a net profit of −35 yuan. Between the 20 yuan gross profit shown in the backend and the actual amount in hand lies a gap of 55 yuan.
The loss-cutoff judgment for this order is straightforward: selling 0.5kg charged weight at 89 yuan cannot achieve positive gross profit in the Europe and US routes. Either raise the selling price to 149 yuan (net profit of about 17 yuan under the same structure), compress the charged weight to within 0.2kg to switch to a light small-item channel, or simply change the product. Among these three actions, only reducing the charged weight by changing the packaging does not require re-validating demand.
Which fields should be included in the minimum profit dashboard and how often should it be updated
No BI tools are needed; a table that allows adding entries by order number is sufficient. Fields are divided into three layers: order layer (order number, SKU, destination country, actual payment received, product cost, charged weight, shipping fee, customs and clearance, platform commission, payment fee), aggregation layer (ad cost allocation, return reserve), and result layer (net profit, net profit margin).
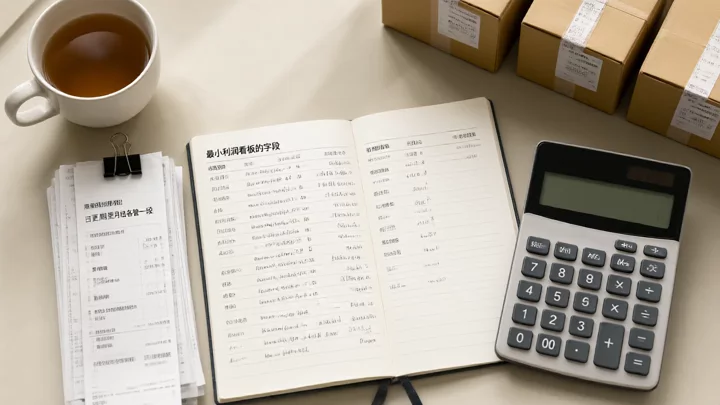
The update cadence follows the data sources: orders and shipping fees update daily because invoice delays are typically only a few days; ad costs and return rates update weekly; customs supplementary payments settle monthly. Include a column labeled “Data Status” in the dashboard to clearly mark which rows are still estimated values, avoiding making decisions based on estimates as if they were facts at month-end.
Two anomaly thresholds are sufficient: if the shipping fee for a single parcel deviates from the quote by more than 15%, trigger a review of charged weight and surcharges; if a specific SKU has negative net profit for two consecutive weeks, pause replenishment and recalculate pricing. The dashboard’s data sources must align with the write scope of the store backend. When operating multiple stores, be especially sure to confirm which account the tool writes to. You can refer toData permission organization for Amazon seller accounts and Seller Central.
Three misjudgments can skew the results of manual calculations
- Relying solely on actual weight for freight quotes.Judgment standard: List the billable weight and actual weight for the last 10 shipments to check the rounding difference. Correction: Add a 'Billable Weight' column to the table for all SKUs, filled in separately by channel.
- Omitting duty back payments.Judgment standard: Check if there was any back payment exceeding the monthly duty estimate in the past six months. Correction: Set up back payment ratios by country and backfill them monthly.
- Using the store's average return rate.Judgment standard: Pull out the three SKUs with the highest return rates and compare them against the average. Correction: Calculate the return reserve by SKU and country.
Rules should be documented on the dashboard rather than kept in your head: Stop restocking SKUs that have had negative net profit for two consecutive weeks, investigate billable weight if the per-ticket freight variance exceeds the quote by 15%, and reassess pricing for that country if the duty back payment ratio rises for two consecutive months.
Common Questions
Should I create a separate profit statement for each country if I ship the same SKU to different countries?
Yes. The unit freight cost, rounding tiers, duty and VAT base, and return rate all vary by country, and combining them into a single line will cause them to offset each other. The practice is to list the same SKU in multiple rows by country, using SKU + Country as the primary key in the dashboard.
Logistics providers quote by the kilogram. Why is the per-ticket cost higher after rounding?
Because chargeable weight is rounded up by tier, 0.38kg is billed as 0.5kg, effectively inflating the unit price. This is compounded by registered mail fees, fuel surcharges, and remote area surcharges, none of which are visible in the per-kg rate. Calculating the effective unit price by dividing the total bill by the total actual weight is the only way to make a fair cross-comparison.
Should customs duty back-payments be recorded in the order period or the back-payment period?
Record in both, but with different purposes: The order period entry serves as a reserve for pricing; the back-payment period entry reflects actual expenditure used to backfill and adjust the reserve ratio. Recording only one side will cause the dashboard to remain inaccurate indefinitely.
Does allocating advertising costs by order or by SKU better reflect true net profit?
By SKU is more accurate. Advertising is typically run at the SKU or campaign group level. Spreading costs evenly across orders misallocates the expense of high-spend bestsellers to organic traffic SKUs. Only if the ad account cannot be split by SKU should you fall back to order-level allocation and manually distribute costs by delivery proportion.

